Staff Reporter
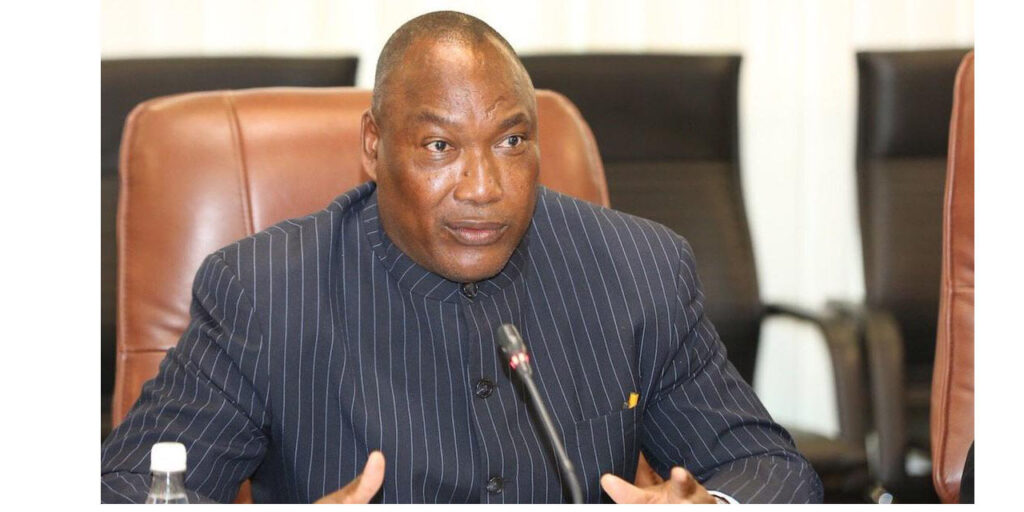
THE Minister of Agriculture, Water and Land Reform, Calle Schlettwein, has said that Namibian High Court Judge, Justice Shafimana Ueitele, applied for and was granted a Land Tax Exemption on the basis that he squarely falls within the categories of former disadvantaged Namibians as articulated under Article 23 of the Constitution of the Republic of Namibia.
Schlettwein made these remarks in response to questions posed by Member of Parliament Lukas Hamata of the Popular Democratic Movement (PDM), who raised questions about the tax exemption granted to the judge, who presided over the Redline case brought forth by Namibian politician Job Amupanda.
“Recent revelations indicate that a serving judge, Shafimana Ueitele, was granted a land tax exemption while presiding over a case in which the first defendant was Mr. Calle Schlettwein himself. This raises serious concerns as to whether the exemption process is being fairly and lawfully administered, or whether it is being used to benefit persons in positions of power,” Hamata queried in parliament.
In response to this, Schlettwein said that the question would have been acceptable were it not for the allegations of unfair and unlawful behaviour against the judge and the minister, which were brought up without a shred of evidence.
“Hon. Hamata deliberately tried to undermine and discredit the judiciary and the executive arm of the republic. He did so in the National Assembly to hide behind the immunity he enjoys in the House. Every member of the National Assembly took an oath to uphold and defend the constitution and laws of Namibia. Hamata took that oath. This deliberate and false discrediting of a Supreme Court judge, and a Cabinet minister, a member of the executive, for collusion for personal gain is not in line with the members’ obligations as per the oath. It harms the good reputation of state institutions and the integrity of both individuals,” Schlettwein said.
He added that the Minister of Agriculture, Water and Land Reform grants Land Tax Exemptions under the provisions contemplated by Article 23(2) of the Namibian Constitution based on a formal application process, which is subject to review and revocation should the conditions for exemption cease to exist. This ensures that exemptions are applied fairly and transparently, in alignment with Namibia’s constitutional and legislative mandates.
In this particular instance, Schlettwein said that on the 29th of April 2022, the Ministry issued a Public Notice in several newspapers informing all farm owners about the Land Tax Assessments for the financial years 2016/17, 2017/18, 2018/19, 2019/20, and 2020/21.
The due date for these payments was the 31st of March 2024. In the same Public Notice, farm owners who met the criteria for exemption, as alluded to earlier, were urged to apply before the 31st of March 2024. The Ministry processed and gazetted all those farm owners who applied and met the Exemption Criteria as outlined above on the 1st of August 2024, as per the provisions of the Act.
He added that Justice Ueitele has two registered farms in the Omaheke region and sold one.
He further stated that the Ministry’s Land Tax Records indicate that during the financial years 2018/19 and 2020/21, Ueitele applied for a land tax exemption and was granted it in respect of his remaining farm, measuring 4867.0781 hectares in the Omaheke.
“It should also be noted that in the financial year 2019/20, with the approval of the National Assembly, it was agreed to impose a zero tax rating on all agricultural commercial farms to ameliorate the negative impacts due to COVID-19. Furthermore, during the financial year 2013/14, the Ministry’s Land Tax records indicate that, as per the law, Mr. Shafimana Fikameni Immanuel Ueitele applied for a Land Tax Exemption on this particular farm and it was granted. However, from the following financial years, that is 2014/15, 2015/16, 2016/17, 2017/18, 2018/19, 2020/21, and 2021/22, our Land Tax records indicate that Mr. Shafimana Fikameni Immanuel Ueitele paid land tax in full, and the Ministry issued him with a Land Tax Clearance Certificate on the 21st of July, 2021. Contrary to what has been implied in this Notice of Question, this factually indicates that the individual in question never exercised his right to apply for Agricultural Land Tax Exemption as provided by the law for those years,” Schlettwein said.