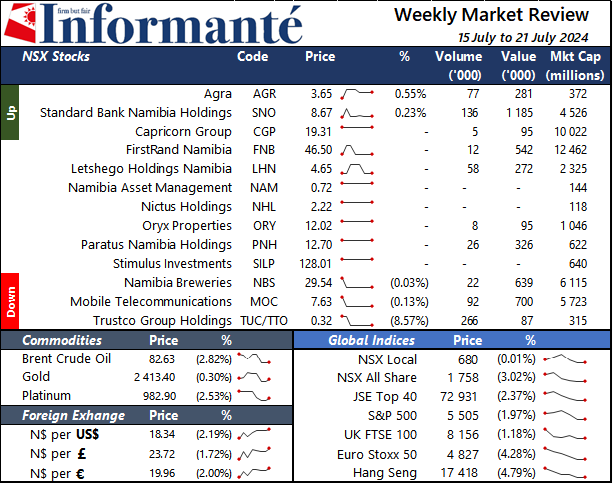
In the week ending July 21, 2024, the Namibian Stock Exchange (NSX) showed a mixed performance, with a slight decline in local stocks and a more significant drop in the overall index. According to the latest market data, the NSX Local index edged down by 0.01% to close at 679.7 points, while the NSX Overall Index experienced a more substantial decrease of 3.02%, ending the week at 1757.8 points. FirstRand Namibia maintained its position as the largest local company on the exchange, boasting a market capitalization of N$12.5 billion. Capricorn Group followed closely with N$10.0 billion, while Namibia Breweries and Mobile Telecommunications rounded out the top four with market caps of N$6.1 billion and N$5.7 billion, respectively. Agra emerged as the top performer for the week, with its shares closing at N$3.65, representing a 0.6% increase. Standard Bank Namibia Holdings secured the second spot, ending the week at N$8.67 per share after a modest 0.2% gain. In terms of trading volume, Standard Bank Namibia Holdings led the market with N$1.2 million worth of shares changing hands. Mobile Telecommunications came in second, recording N$0.7 million in share trades. On the currency front, the Namibian dollar faced significant headwinds against major global currencies. It depreciated 2.19% against the US dollar, closing at N$18.34 per USD. The local currency also weakened against the British pound, losing 1.72% to end at N$23.72 per GBP. Against the euro, the Namibian dollar fell by 2.00%, closing the week at N$19.96 per euro.
In June 2024, Namibia’s new vehicle sales showed mixed results, with overall sales increasing 2.7% month-on-month to 993 units but declining 23.3% year-on-year. This decline is partly attributed to a high base effect, as June 2023 had the highest sales since March 2017. The first half of 2024 saw total sales of 6,316 vehicles, marginally lower than the 6,331 sold in the same period of 2023. However, the 12-month cumulative sales figure of 12,514 units represents a 4.6% increase year-on-year, indicating a generally robust market despite short-term fluctuations. The commercial vehicle segment demonstrated strength, particularly in light and heavy commercial vehicles, which saw year-to-date increases of 8.9% and 10.3% respectively. This performance is expected to underpin the overall market’s stability in the near term, driven by demand from sectors such as construction and logistics. In contrast, passenger vehicle sales faced headwinds, declining 29.2% year-on-year in June.